Law Smith
Founder & President, Tocobaga
Law Smith is the Founder and President of Tocobaga, a Tampa-based ROI-focused marketing agency and SMB advisory. He has strategically advised 1,000+ small and medium businesses, executed 600+ integrated marketing campaigns, and written 30+ business plans across industries ranging from professional services to e-commerce to B2B technology. Tocobaga is a Google Partner and Squarespace Gold Partner headquartered in Ybor City.
On the morning of April 18, 1906, a massive earthquake hit San Francisco, and then the city caught fire.* A banker in his mid-30s named Amadeo Peter Giannini, A.P. to everyone, ran a bank not yet two years old, the Bank of Italy, out of North Beach. He was a former produce merchant, not a blue blood.† His customers were immigrants and working people, the borrowers most bankers of the day considered not worth the paperwork. Giannini had a different read. He found they repaid their debts just as reliably as the rich.*
As the fire crept toward his building, Giannini loaded the bank's money into two wagons, about $80,000 in gold and silver coin, and buried it under crates of oranges and vegetables.*,‡ Then he drove it past looters and out of the burning city to his family's home in San Mateo.*,‡ The fire took the building. It did not take the money.
The big downtown banks had the opposite problem. Their vaults survived, but the heat had turned the steel into ovens, and nobody dared open a door for weeks, because a rush of oxygen could ignite the cash and records inside.* The marble lobbies were still standing, more or less. The banks inside them could not lend a nickel.
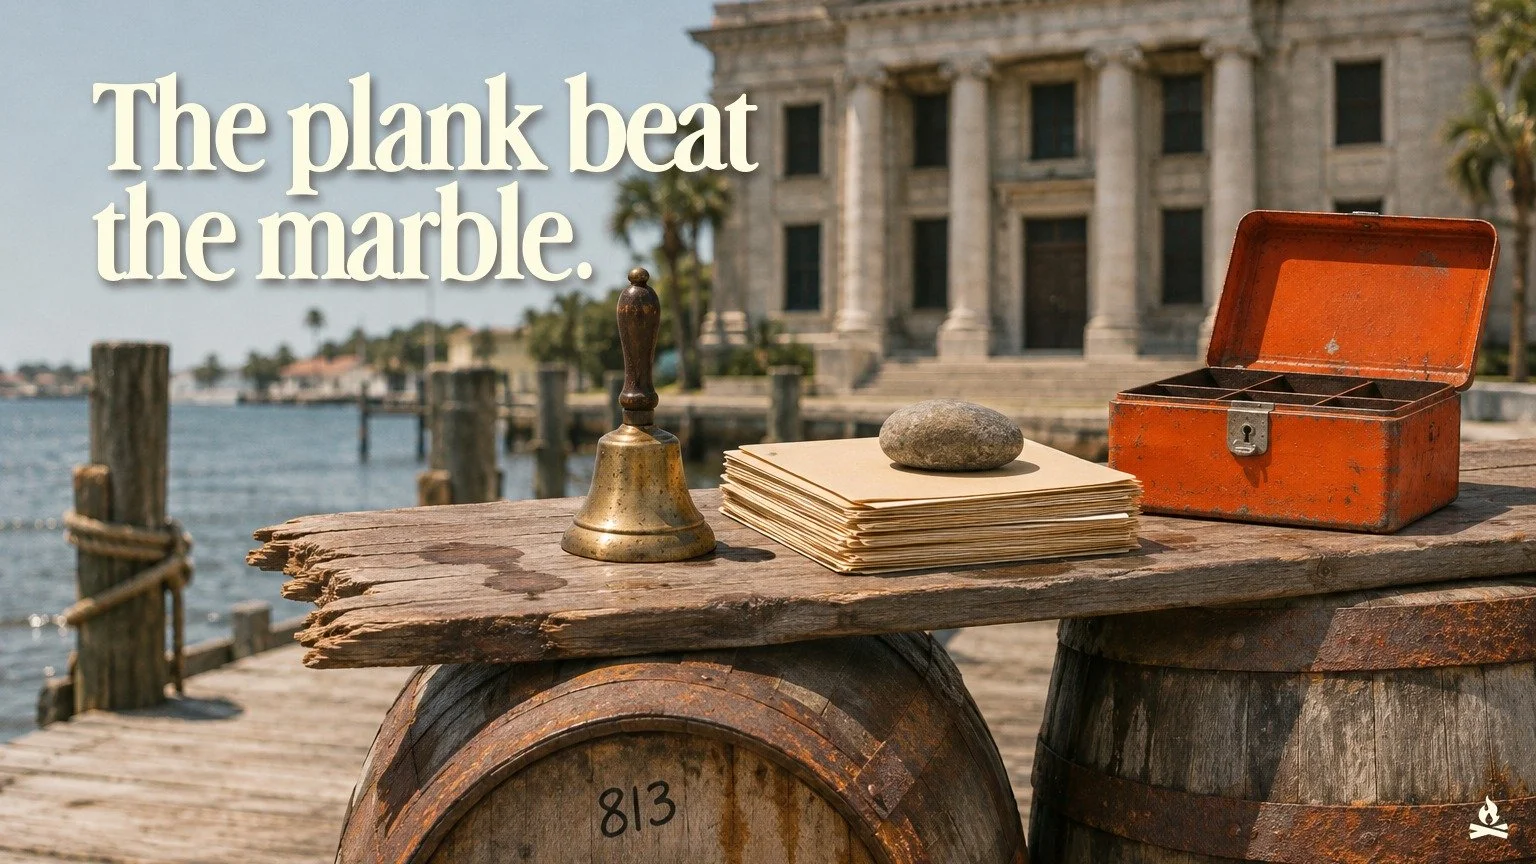
Giannini could. He set up shop on the Washington Street wharf with a counter made from a plank laid across two barrels, and he made loans on a handshake to people who wanted to rebuild.‡,†,* The Bank of Italy was back in business within nine days of the quake, well ahead of the city's other banks.‡ On November 1, 1930, it became Bank of America, and when Giannini died in 1949 it had more than 500 branches, $6 billion in assets and the title of largest bank in the world.*
The usual lesson from the plank and the barrels is courage. The better lesson is information. The lender with the nicer building had the vault. The lender on the wharf had the cash, the relationships and the willingness to show up. Only one of them was useful that week.
Owners are living a quieter version of that week right now. On September 16, 2026, the Federal Reserve raised its benchmark rate a quarter point to a range of 3.75 to 4.00 percent, its first hike since 2023, and big banks moved the prime rate from 6.75 to 7.00 percent the next day.§,‖ SBA rules tightened in 2025 and changed again on October 1, 2026.¶,** The question on Reddit and X has not changed: where is anyone actually getting usable capital for a truck, a machine or a second location when the bank is slow and the SBA feels like a months-long maze?
Tocobaga is not a lender. Tocobaga, the marketing agency and SMB advisory behind SolvingHow.com, works out of Ybor City in Tampa, and Law Smith, its founder and president, has written more than 30 business plans, the kind of document that lands on a loan officer's desk. That seat shows something most finance content misses: the money is rarely the hardest part. The hardest part is being a borrower a lender can read. What follows is a ranked, honest map of where usable capital comes from in late 2026, what each source really costs, and how to look like Giannini's best customer instead of a stranger at the wharf. It is a field map, not financial, legal or tax advice. A CPA and a banker get the last word.
What are the best small business financing options right now?
The best small business financing options in late 2026, ranked by approval odds and true cost, start with a community bank or credit union, then SBA 7(a) and 504 loans, then equipment and vendor financing, then business lines of credit and cards. CDFIs, revenue-based financing, online lenders and invoice factoring fill specific gaps, and merchant cash advances sit at the bottom, used rarely and only with a calculator open.
The demand is real. In the Federal Reserve Banks' 2026 Report on Employer Firms, built on 6,525 responses, 60 percent of firms applied for some kind of financing in the prior 12 months, and 38 percent applied for a loan, line of credit or merchant cash advance.†† Only 42 percent of applicants received the full amount they sought. Another 36 percent got some of it, and 22 percent got nothing.††
Put ten applicants in a room. Four walk out with everything they asked for. Two walk out empty-handed. The other four get a partial yes, which is often the most dangerous outcome, because a business that needed $150,000 and got $90,000 tends to fill the gap with the most expensive money in town. The partial yes is where merchant cash advances find their best customers.
The reasons for borrowing matter too. The same survey found 56 percent of applicants were trying to meet operating expenses, while 46 percent were pursuing an expansion or a new opportunity.†† Those are different problems. Borrowing to grow can pay for itself. Borrowing to cover payroll is borrowing against a hole, and the lender knows it. The ranking below reflects four tests: what the money costs in dollars, how fast it arrives, how likely a full yes is, and what happens to the owner if the plan goes sideways.
Community bank or credit union: best full-approval odds, lowest cost, slowest start.
SBA 7(a), Express and 504: long terms, capped rates, heavy paperwork.
Equipment and vendor financing: the machine is the collateral.
Business line of credit or card: cheapest when arranged early.
CDFI loan: for bankable but unusual borrowers.
Revenue-based financing: payments flex with sales, at a premium.
Online lender: fast, but the price is often a surprise.
Invoice factoring: cash today for invoices due in 60 days, at a discount.
Merchant cash advance: fastest money, highest cost, last resort.
Customer-funded growth: deposits, retainers and prepaid plans, with no interest at all.
| Source | Speed | Cost or approval signal | Best use |
|---|---|---|---|
| Community bank or credit union | Weeks; faster with an existing relationship | 57% of small-bank applicants fully approved (Fed SBCS, 2026) | Term loans and lines for established firms |
| SBA 7(a), Express and 504 | Weeks to months; SBA review 2 to 10 business days | Rates capped at prime plus 3 to 6.5 points (SBA) | Acquisitions, real estate, long-term growth |
| Equipment and dealer financing | Days to weeks | 77.7% industry approval rate (ELFA, September 2026) | Trucks, machines, forklifts, technology |
| Business line of credit | Weeks to open, same day to draw | Interest only on the amount drawn | Payroll gaps, seasonal swings, slow receivables |
| CDFI loan | Weeks | 1,383 Treasury-certified CDFIs (CDFI Coalition, 2026) | Bankable but unconventional borrowers |
| Online lender | Days | 60% of borrowers say costs ran higher than expected (Fed SBCS, 2026) | Short needs with a known repayment event |
| Revenue-based financing | Days to weeks | A 1.3x cap repaid in 12 months is about 51% APR | High-margin e-commerce and SaaS |
| Invoice factoring | Days | 2.5% per 30 days is about 30% annualized | B2B firms with slow but reliable customers |
| Merchant cash advance | Days | A 1.35 factor over 8 months is about 95% APR | Last resort, never stacked |
Are credit unions and community banks easier for a business loan?
By the numbers, small banks are the most likely to say a full yes. In the Federal Reserve Banks' 2026 survey, applicants at small banks were more likely to be fully approved, at 57 percent, than applicants at any other kind of lender.††
Credit unions are moving into the same territory fast. As of June 30, 2026, federally insured credit unions held $201.7 billion in commercial loans, up 10.1 percent in a year, while their total lending grew 4.9 percent.‡‡ Business lending is growing at roughly twice the pace of everything else credit unions do. There are 4,214 federally insured credit unions serving 146.1 million members, and plenty of owners already belong to one without ever having asked the business lending desk a single question.‡‡
The reason local lenders approve more often is the Giannini reason. A community banker in Brandon or a credit union lender in Lakeland can know the borrower. That banker has watched the operating account for three years, knows the owner's spouse runs the books, and drove past the new warehouse on the way to lunch. A national bank underwriter in another state sees a credit file and a tax return. Same borrower, very different picture.
There is a movie version of this too. In It's a Wonderful Life (1946), a panicked crowd storms the Bailey Building and Loan demanding cash, and George Bailey explains that the money is not sitting in a vault. It is in Joe's house, the Kennedy house and a hundred others in town, lent to neighbors. Relationship lending works because the lender's money and the borrower's life are in the same zip code.
The trade-offs are real. Community banks and credit unions often want two or three years of tax returns, interim financial statements, a personal guarantee and collateral. A credit union business loan usually requires membership first. The fix is timing. The relationship has to exist before the need does: the operating account, the merchant services, the annual coffee with the commercial lender, the quarterly financials sent without being asked. Giannini made handshake loans on the wharf because he already knew whose hand he was shaking.
How long does an SBA loan take, and what changed in 2026?
An SBA 7(a) loan usually takes several weeks to a few months from first meeting to funding, and most of that time is spent with the lender, not the SBA. The SBA lists its own turnaround at 5 to 10 business days for a Standard 7(a) and 2 to 10 business days for a 7(a) Small Loan, but packaging, underwriting, appraisals and closing stretch the calendar well beyond that.§§
A Standard 7(a) goes up to $5 million with a guarantee of up to 75 percent. A 7(a) Small Loan tops out at $350,000. SBA Express goes up to $500,000 with a 50 percent guarantee, trading a thinner guarantee for faster lender decisions.§§ In fiscal 2026 the SBA approved 56,130 7(a) loans totaling $32.4 billion and 6,075 504 loans totaling $7.1 billion, a year interrupted by a 43-day federal shutdown.‖‖ Divide it out and the average 7(a) loan ran about $577,000 and the average 504 loan about $1.17 million. The program mostly serves established businesses buying something substantial.
Rates are capped, and the caps move with prime. For variable-rate 7(a) loans, the maximum spread is 6.5 points over the base rate at $50,000 or less, 6.0 points from $50,001 to $250,000, 4.5 points from $250,001 to $350,000, and 3.0 points above $350,000.¶¶ With prime at 7.00 percent after the September hike, those ceilings land at 13.5, 13.0, 11.5 and 10.0 percent.‖ A $40,000 SBA loan can legally cost more than a $400,000 one.
The rules changed twice in 16 months. SOP 50 10 8, effective June 1, 2025, largely reinstated pre-2021 underwriting.¶ Startups and changes of ownership now need at least a 10 percent equity injection from the buyer. A seller note counts toward that injection only if it sits on full standby for the life of the loan and makes up no more than half of the injection. Businesses must be 100 percent owned by U.S. citizens or U.S. nationals, and since March 1, 2026, lawful permanent residents no longer qualify.*** A seller who rolls equity into the deal must personally guarantee the loan for two years.¶ Then the SBA retired the FICO SBSS score for 7(a) Small Loans on March 1, 2026, and told lenders the debt service coverage ratio on those loans must be at least 1.10 to 1, on a historical or projected basis.†††
SOP 50 10 8.1 took effect October 1, 2026, for applications that receive an SBA loan number on or after that date.** It revises the equity and underwriting standards for business acquisitions and owner buyouts, lets lenders finance part of an eligible acquisition through a revolving line of credit, gives SBA Express lenders more room to extend and reissue loans, and expands the MARC program to more industries.**
Those acquisition rules matter beyond Main Street. PE-backed platforms usually fund add-ons through their own credit facilities, but the founders they court are often weighing an offer from an SBA-financed buyer at the same time. The 10 percent injection and the standby seller-note rule change what those competing offers look like, and how much cash the seller actually walks away with at closing. Tocobaga's earlier piece on private equity buying small businesses, Same Name on the Truck, covers the seller's side of that table.
Is a business line of credit or a business credit card better for working capital?
A business line of credit is usually better for working capital, because it carries a lower rate than a carried card balance and charges interest only on what is drawn. A business credit card is better for small, short purchases paid off inside the grace period; carried month to month, it becomes some of the most expensive credit an owner can use. A card is a wallet, not a financing plan.
Short-term money is getting pricier, which makes the cheap version worth arranging early. The NFIB's September 2026 survey put the average rate owners paid on short-term loans at 8.2 percent, up 0.7 points in a single month, and only 22 percent of owners said they borrow regularly, against a historical average of 34 percent.‡‡‡
The line is the shock absorber. Consider a two-partner estate planning firm in Clearwater with a $100,000 line at 9.5 percent. A slow February leaves a $40,000 hole in payroll and rent until probate fees land in April. Drawing $40,000 for 60 days costs about $625 in interest. That is the price of a nice dinner for the partners, not a crisis. The same firm without a line ends up asking a vendor for terms, or worse, taking a cash advance that costs ten times as much.
Lines have rules. Banks usually review them every year, many want to see the balance paid down to zero at some point during the year, and most ask for a personal guarantee. Among firms with debt, 59 percent used a personal guarantee to secure it, and 51 percent pledged business assets.†† The SBA offers CAPLines for seasonal and contract-driven working capital, with maturities up to 10 years, for businesses that want the guarantee behind a revolving structure.§§
The single most important fact about a line of credit is when to ask for it. Banks lend against strength. The best time to open a line is the month the books look great and nothing is wrong, which is exactly the month most owners feel they do not need one. By the time the hole shows up, the financials show the hole too. Giannini's plank only worked for faces he already knew, and a line is the modern version of being known before the fire.
Is equipment financing easier to get than a business loan?
Usually, yes. Equipment financing is secured by the machine itself, so lenders can approve faster and ask for less collateral elsewhere, and the industry is busy: the Equipment Leasing and Finance Association's CapEx Finance Index showed new business volume up 17.0 percent year to date through September 2026, with an average credit approval rate of 77.7 percent.§§§
ELFA's acting president and CEO, James Cress, said it is becoming hard to describe just how strong deal volumes have been this year.§§§ The same report carried good news on credit: the approval rate climbed 2.4 points in a single month, the largest monthly gain since October 2023.§§§ Lenders are still writing deals, and more of those files are getting a yes.
Equipment money comes in three flavors. Bank and credit union equipment loans usually price best. Captive and dealer financing, where the manufacturer's finance arm writes the paper at the point of sale, can be the fastest yes in the building and sometimes carries promotional rates. Leases trade ownership for lower payments, with a $1 buyout lease behaving like a loan and a fair market value lease behaving like a rental. For a manufacturer or a 3PL, the right choice depends on whether the asset holds value or gets replaced on a cycle.
The tax code currently tilts the math toward buying. For 2026, the Section 179 expensing limit is $2,560,000, with the phaseout starting above $4,090,000, and the 2025 tax law reinstated 100 percent bonus depreciation for qualified property acquired and placed in service after January 19, 2025.‖‖‖ A Grand Rapids contract machine shop buying a $600,000 five-axis machining center may be able to deduct the full cost in the year it goes into service, which changes the after-tax weight of every monthly payment. The CPA decides whether that applies; the owner's job is to ask before signing.
A Tampa 3PL offers the simpler version. Say a new shipper account adds $14,000 a month in storage and handling revenue and needs one more electric forklift at $45,000. Financed over 60 months at 9.5 percent, the payment is about $945 a month, under 7 percent of the new revenue it supports. The forklift pays for itself in the first week of each month. That is what good debt looks like: a specific asset tied to a specific stream of cash.
How much does a merchant cash advance really cost?
A merchant cash advance usually costs far more than its factor rate suggests, because the fee is charged on the full advance while the balance shrinks with every daily debit. A 1.35 factor rate on $80,000, repaid over eight months of business days, works out to an annual percentage rate of roughly 95 percent, and about 126 percent if sales run hot and it is repaid in six.
The mechanics explain the price. A merchant cash advance is generally structured as a purchase of future receivables, not a loan. The provider hands over a lump sum and collects a fixed total, the advance times the factor rate, through daily or weekly debits from the bank account or a cut of card sales. A 1.35 factor rate sounds like 35 percent. But the owner never has the full $80,000 for the full term. By month four, half of it has been paid back while the fee keeps running on the original number. That is why the effective APR lands near triple digits.
The second advance is where it gets ugly. When daily debits squeeze cash flow, the easiest fix on offer is a renewal or a second advance stacked on top of the first, often from a different provider. Each one is priced on the stressed cash flow the last one created.
It's a Wonderful Life saw this coming too. During the run on the Building and Loan, old Mr. Potter offers to buy the panicked depositors' shares for 50 cents on the dollar. It is fast. It is available. It solves the problem by the end of the afternoon. It is also a terrible price, and George Bailey talks the crowd out of it with his own $2,000 honeymoon money, closing the day with $2 left in the drawer. A merchant cash advance is Potter's offer with a nicer website.
Disclosure laws now force some of the math into daylight, unevenly. New York's commercial finance disclosure regulations, finalized in February 2023, require providers of financing of $2.5 million or less to disclose annual percentage rates, including estimated APRs for non-loan products such as sales-based financing.¶¶¶ California, Utah and Virginia also have disclosure regimes on the books.¶¶¶ Florida's Commercial Financing Disclosure Law covers transactions of $500,000 or less consummated on or after January 1, 2024, and requires the total funds provided, the dollar cost of financing, the payment schedule and any prepayment penalties, but it does not require an APR.**** Violations carry fines of $500 per incident, capped at $20,000 for aggregated violations.**** A Tampa owner gets a dollar figure, not a rate, and has to run the conversion alone.
Merchant cash advance or equipment loan: what does the math say for a Tampa HVAC contractor?
For a Tampa HVAC contractor borrowing $80,000 for two upfitted service vans, an equipment loan at 9.5 percent costs about $4,800 in interest over the first eight months, while a merchant cash advance at a 1.35 factor rate costs $28,000 over the same eight months and pulls about $13,500 a month out of the operating account. The loan funds growth. The advance eats the growth it was supposed to fund.
The setup: a nine-truck residential HVAC company in Town 'n' Country is turning away July calls. Two more upfitted vans and the techs to run them would add capacity of about four calls a day per van, or roughly 168 calls a month across 21 working days. The bank wants three weeks and a stack of documents. A merchant cash advance broker promises money by Friday. The owner needs $80,000.
Option A is the merchant cash advance. The provider funds $80,000 at a 1.35 factor rate, so the business owes $108,000. If the holdback clears that total over eight months, about 168 business days, the daily debit is about $643, or roughly $13,500 a month. The fee is $28,000. Solving for the rate that makes 168 daily payments of $643 equal an $80,000 advance gives an effective APR of about 95 percent. If July and August run hot and the advance clears in six months, the daily debit climbs to about $857 and the effective APR rises to about 126 percent.
Option B is an equipment loan. The same $80,000 over 60 months at 9.5 percent, a rate roughly 2.5 points over today's prime, carries a payment of about $1,680 a month. Over the first eight months the business pays about $13,440, of which roughly $4,830 is interest and the rest goes to principal. Over the full five years, total interest comes to about $20,800, still less than the advance charges in eight months.
The gap that matters is monthly cash. The advance takes about $11,800 more out of the account each month than the loan does. Assume an average service ticket of $450 at a 45 percent gross margin, or about $200 of gross profit per call. Covering that $11,800 gap takes about 59 extra calls a month. The two new vans handle about 168 calls a month, so roughly 35 percent of the new capacity would be working for the advance instead of the business. That is before a slow September, a tech who quits or a compressor warranty claim.
Merchant cash advance: $80,000 in, $108,000 out, about $643 per business day, effective APR of about 95 percent.
Equipment loan: $80,000 in, about $1,680 a month for 60 months, 9.5 percent APR, about $20,800 total interest.
Eight-month cost: about $28,000 for the advance versus about $4,830 in interest on the loan.
Monthly cash difference: about $11,800, or 59 service calls at $200 of gross profit each.
There is one more line in the loan's favor. If the vans qualify for bonus depreciation or Section 179 expensing, the business may deduct their cost in the first year, which can lower the tax bill enough to cover several loan payments.‖‖‖ An advance funds the same vans, of course, but it drains the cash that tax savings would have protected. The honest conclusion is simple. When the asset can secure the money, the asset should secure the money. The three-week wait for the cheaper loan is not the cost. The cost is $23,000 of difference in eight months.
What is the strongest case for fast online lenders over the bank?
The strongest case is that time has a price too. A business that loses a $200,000 contract while waiting two months for cheaper money has paid a cost that never appears on an amortization schedule, and owners know it: the share of firms applying to online lenders has risen for five consecutive survey years and is now about the same as the share applying at small banks.††††
The argument deserves a fair hearing. Online lenders decide fast, often within days, because they underwrite from bank feeds and card processing data instead of a stack of tax returns. They will look at a two-year-old business with a thin file that a community bank would decline on time in business alone. Firms told the Federal Reserve they went to online lenders for faster decisions and a better chance of being funded.†††† For a short, self-liquidating need, the speed can be worth the premium.
Run the steelman with real numbers. A Shopify brand doing $4 million a year needs $250,000 of inventory ten weeks before the holidays, backed by last year's sell-through. If that inventory turns into $600,000 of revenue at a 58 percent gross margin, it throws off about $348,000 of gross profit. A $20,000 financing fee for a 90-day product is expensive as a rate and cheap as a share of the profit it enables. The bank's 60-day process would have missed the season entirely. In that narrow case, fast money is the right money.
Now the counterargument, which is also the data. Sixty percent of firms that borrowed from online lenders said their actual borrowing costs were higher than expected, compared with 37 percent at small banks and 32 percent at large banks.†† The problem is not that fast money is expensive. Everyone knows that going in. The problem is that it is expensive in ways the owner did not model: origination fees, weekly payments that push the effective rate higher, prepayment terms that keep the full fee even when the balance is paid early.
The rule that falls out of both sides is clean. Fast money works when there is a known repayment event, a purchase order, a seasonal sell-through, a signed contract, and the dollar cost is smaller than the margin it protects. Fast money fails when it is plugging an operating hole with no repayment event in sight. Giannini lent fast on the wharf, but he lent to people with a plan to rebuild, not to people hoping the fire would go out on its own.
What are the best alternatives to SBA loans when the money is needed in weeks?
The best alternatives to SBA loans for speed are equipment and dealer financing, a bank or credit union line already in place, CDFI loans for borrowers who are bankable but unconventional, revenue-based financing for high-margin online and subscription businesses, and invoice factoring for B2B companies waiting on slow-paying customers. Each fits a specific situation, and each is a poor fit outside it.
CDFIs, community development financial institutions, are the most overlooked of the group. There are 1,383 Treasury-certified CDFIs, and recipients of CDFI Fund program awards financed more than 109,000 businesses in fiscal 2024, part of almost $24.5 billion in total loans and investments that year.‡‡‡‡ They bring in over $8 of private capital for every $1 of federal support.‡‡‡‡ A CDFI will often lend to the owner a bank turns down for reasons that have little to do with repayment, like a short credit history, a recent move or an industry the bank does not understand, and many attach business coaching to the loan.
Revenue-based financing trades fixed payments for a share of monthly revenue until a set cap is repaid. It suits e-commerce brands and SaaS companies with healthy gross margins and lumpy months. The cost hides in the cap and the speed. A $300,000 advance with a 1.3 times cap means $390,000 repaid. If that happens over 12 months, the effective APR is about 51 percent. Over 18 months it is about 35 percent. For a VC-backed SaaS company that would otherwise sell equity at a down-round price, that can still be the cheaper money. For a services firm with thin margins, it is a slow leak.
Invoice factoring sells receivables at a discount. A factor typically advances most of an invoice's value up front and keeps a fee that grows the longer the customer takes to pay. Picture a Tampa 3PL carrying $200,000 of invoices to shippers on net-60 terms. A factoring fee of 2.5 percent per 30 days costs $10,000 for those 60 days, which annualizes to roughly 30 percent. The same $200,000 drawn on a 9.5 percent line of credit for 60 days costs about $3,120. Factoring is the right call when the line is maxed or does not exist yet, and when the customers are large and reliable, like the big-box retailer paying a manufacturer on net-90 or the national shipper paying a regional carrier. It is a bridge, not a home.
How do lenders decide whether to approve a small business loan?
Lenders decide mostly on cash flow, then on collateral and the owner's personal guarantee, then on the story the numbers tell. The core test is debt service coverage, which is operating cash flow divided by loan payments, and for SBA 7(a) Small Loans the floor is 1.10 to 1, on either a historical or projected basis.†††
The arithmetic is unforgiving. A business whose existing and proposed loan payments total $96,000 a year needs $105,600 of operating cash flow to clear a 1.10 ratio. A bank that wants a thicker cushion, say 1.25, needs to see $120,000. The difference between a yes and a no on a mid-size loan is often $15,000 of documented cash flow, which is exactly the kind of number that disappears when an owner runs personal expenses through the business to save on taxes. The deductions that look smart in April look expensive in the loan file.
Collateral and guarantees come next. Among firms with debt, 59 percent used a personal guarantee and 51 percent pledged business assets.†† For most small businesses, the personal guarantee is not a negotiation; it is the price of admission. SBA rules do exempt equity investors owning less than 20 percent from guaranteeing in a full change of ownership.¶
Credit scoring is shifting under the surface. With the SBSS score retired for 7(a) Small Loans on March 1, 2026, lenders now use scoring models permitted by their federal regulator, and those models cannot rely solely on consumer credit scores.††† That puts more weight on business data: bank statements, receivables aging, customer concentration and time in business. In some cases lenders may accept CPA-prepared or reviewed financial statements instead of tax returns.¶
Giannini understood underwriting as fieldwork. When he built the country's first statewide branch system, he walked in the rows beside farmers who were plowing, explaining how branches would make their credit cheaper and more reliable.* Few bankers walk the rows now. So the borrower has to carry the rows to the bank: the backlog, the contracts, the customer list, the marketing numbers that show where next year's revenue comes from.
Can marketing data help a small business get approved for a loan?
Yes. Marketing data does not replace tax returns, but it answers the question underwriters worry about most: where the next 24 months of revenue will come from. A clean pipeline report with cost per lead, close rate, customer acquisition cost and lifetime value turns a projection into evidence, and evidence is what moves a file from maybe to yes.
The need is obvious in the Fed's own numbers. Reaching customers and growing sales was the top operational challenge employer firms reported in the 2026 survey, ahead of hiring.†† Every lender reading a growth loan application is quietly asking the same thing: does this owner know how to get customers, or is the projection a hope with a spreadsheet attached?
Take the Clearwater estate planning firm again. Its marketing spends $36,000 a year and produces 120 paid consultations. Thirty-eight percent become clients at an average engagement of $4,200, which is about 46 new clients and $191,520 in revenue. That makes the customer acquisition cost about $790 per client against $4,200 of first-year revenue, a ratio better than 5 to 1, before counting referrals and the later trust administration work. When the partners ask for a loan to hire a third attorney, that page answers the repayment question better than any projection could. The lender is not betting on optimism. The lender is betting on a machine that already runs.
The same logic scales up. A home services company can show maintenance plan renewal rates and booked jobs for the next 90 days. A manufacturer can show quote volume, win rate and backlog by customer. A PE-backed platform refinancing its credit facility is already reporting EBITDA to its lenders, and marketing efficiency is a leading indicator of where that EBITDA goes next. The common thread is proof that revenue is produced on purpose, not found by accident.
Cost per lead by channel, trailing 12 months.
Lead-to-customer close rate, by service line.
Customer acquisition cost and average first-year revenue per customer.
Repeat and renewal rates, the retention evidence lenders love.
Booked backlog or signed contracts for the next two quarters.
Most owners cannot produce those five numbers on demand, and that is the real gap. Tocobaga's earlier piece on proving marketing ROI, The Map Is Not the Pump, explains how to build the reporting that makes them easy to pull. A lender will rarely ask for them by name. A lender will almost always notice when they are there.
How can a small business fund growth with customer money instead of debt?
By getting paid before the work is done: deposits, retainers, prepaid maintenance plans, memberships and annual contracts paid up front. Customer-funded growth costs nothing in interest, and it delivers something no lender can provide, proof of demand that shows up in the bank account before the expense does.
More owners are choosing this path, or at least choosing less debt. The share of employer firms with no outstanding debt reached 31 percent in the 2026 survey, up from 21 percent in 2020.†† Some of that is caution after rate hikes. Some of it is owners who learned that the cheapest capital is the customer's.
The HVAC version is the maintenance plan. A contractor with 600 members paying $199 a year collects $119,400 in predictable revenue, much of it in the slow shoulder months when cash is tightest. Those members also call that contractor first when a system dies, which turns a $199 plan into the inside track on a $12,000 replacement. A custom manufacturer can ask for a 30 to 50 percent deposit on a build-to-order job, which funds the raw materials before the first cut. A consulting firm can bill a monthly retainer instead of chasing invoices at the end of a project. A SaaS company can offer a modest discount for annual prepayment and collect a year of cash in month one.
None of this works without trust. Customers prepay businesses they believe will still be there in a year. That is why customer-funded growth rewards the same things good marketing builds: reviews, visible proof and a reputation for showing up. Tocobaga's piece on retention math, Norm's Stool Pays the Rent, makes the case that the repeat customer is the most valuable asset most service businesses own. A prepaid plan is that idea with a deposit slip attached.
George Bailey had the right idea in that 1946 bank run. The Building and Loan survived because its depositors and its borrowers were the same people, and on the worst day they took only what they needed. A business funded by its own customers runs on that loop. The money is in Joe's house, and Joe keeps renewing.
What should an owner do before applying for business financing?
An owner should build the lender relationship, clean up the books and assemble proof of repayment months before the money is needed, because lenders lend against strength and the application reflects the last 12 months, not the next 12. The steps below turn a cold application into a warm one.
Open the operating account and merchant services at the bank or credit union most likely to lend, at least 12 months before the ask.
Meet a commercial lender in person while nothing is wrong, and ask what a strong file looks like at that institution.
Move the books to clean monthly closes with a CPA review, and stop running personal expenses through the business.
Calculate debt service coverage with the new payment included, and aim for a cushion above 1.25, not a scrape past 1.10.
Ask for a line of credit during a strong quarter, before any hole appears.
Write a one-page use of funds that ties every dollar to an asset, a contract or a revenue stream, with the payback math shown.
Assemble the five marketing numbers: cost per lead, close rate, acquisition cost, retention and booked backlog.
Convert every offer into an APR and a total dollar cost, especially in Florida, where sales-based financing disclosures show dollars rather than rates.
Read the personal guarantee, collateral and prepayment terms before signing, not after.
Never stack a second cash advance on top of the first.
The list is not glamorous. Neither was a plank on a wharf. What made the wharf work was everything that happened before the earthquake: years of knowing customers well enough to lend on a handshake.
Who helps a small business get lender-ready without selling it a loan?
The best help comes from people who earn nothing from the loan itself: a CPA, a commercial banker who wants the relationship, a Small Business Development Center advisor or SCORE mentor, and an advisor who can turn the business's marketing and sales data into evidence a lender respects. Brokers paid on funded deals are useful for access, but their incentive is the closing, not the cost.
Tocobaga sits in that last seat. The firm is a marketing agency and SMB advisory, not a lender or a broker, and it has advised more than 1,000 small and mid-sized businesses, written more than 30 business plans and executed more than 600 integrated campaigns. The work that matters in a financing year is specific: a business plan built for an underwriter's eyes, marketing reporting that shows cost per lead and acquisition cost by channel, and a pipeline view that turns a growth projection into a pattern. An intro call is the simple first step, at (813) 534-1261 or hello@solvinghow.com through SolvingHow.com. Tocobaga works on flat fees, never charges a percentage of ad spend, does not auto-renew contracts, and the client owns every account and asset. Tocobaga is not for everyone, and when it is not the right fit it says so and points to someone who is.
What would A.P. Giannini see in a borrower in 2026?
He would see the same thing he saw from the wharf in 1906: whether the person across the plank had a real plan to rebuild and a track record of paying what they owed. The tools changed. The question did not.
He would probably like the credit union lender who knows the owner's name, and the equipment dealer who will write the paper on the spot because the machine itself is the collateral. He would understand the SBA, with its capped rates and long terms, as a slower version of what he did on the waterfront. He would recognize the merchant cash advance immediately. Every disaster has someone selling money at 50 cents on the dollar to people too scared to wait.
The owners who come through 2026 in good shape will not be the ones who found the magic lender. They will be the ones who did the boring work early: the relationship before the need, the clean books, the line opened in a good quarter, the marketing numbers that prove revenue arrives on purpose. When the next fire comes, and it always does, the marble lobbies will lock their vaults and wait for the steel to cool.
The money that mattered in San Francisco did not come from the building with the columns. It came from a plank, two barrels and a banker who already knew whose hand he was shaking. The whole game, then and now, is being the hand the banker already knows.
What is the easiest business loan to get?
Equipment financing is usually the easiest business loan to get, because the equipment itself secures the debt; the Equipment Leasing and Finance Association reported an industry approval rate of 77.7 percent in September 2026. For full approval on general business credit, small banks led the Federal Reserve Banks' 2026 survey at 57 percent. Merchant cash advances are easier still, but their effective cost can approach triple-digit APRs, so easy and affordable are two different things.
Are merchant cash advances bad?
Merchant cash advances are legal and occasionally useful, but they are the most expensive mainstream financing a small business can take. A 1.35 factor rate repaid through daily debits over eight months equals an effective APR of roughly 95 percent. They make sense only as a short bridge with a known repayment event. Stacking a second advance to cover the first is the pattern that sinks businesses. Florida requires dollar-cost disclosure but not an APR, so owners should convert the offer themselves.
What are current SBA loan rates?
SBA 7(a) rates are negotiated with the lender but capped by the SBA. For variable-rate loans the maximum is prime plus 6.5 points at $50,000 or less, plus 6.0 points up to $250,000, plus 4.5 points up to $350,000 and plus 3.0 points above that. With prime at 7.00 percent after the Federal Reserve's September 16, 2026 rate hike, those ceilings are 13.5, 13.0, 11.5 and 10.0 percent.
How much equity is needed for an SBA loan to buy a business?
Under SOP 50 10 8, effective June 1, 2025, SBA 7(a) loans for startups and changes of ownership require at least a 10 percent equity injection from the buyer. A seller note counts toward that injection only if it is on full standby for the life of the loan and makes up no more than half of the injection. SOP 50 10 8.1, effective October 1, 2026, revised the equity and underwriting standards for acquisitions, so buyers should confirm current terms with an SBA lender.
Do credit unions make small business loans?
Yes, and the volume is growing. Federally insured credit unions held $201.7 billion in commercial loans at June 30, 2026, up 10.1 percent in a year, according to NCUA data. A credit union business loan usually requires membership first, and underwriting often resembles a community bank's: tax returns, financial statements, a personal guarantee and collateral. Owners who already bank with a credit union start with an advantage, because the lender can see their account history.
What is a good debt service coverage ratio for a business loan?
The SBA requires at least 1.10 to 1 for 7(a) Small Loans, measured on a historical or projected basis, and a lender wanting a thicker cushion may set a higher bar, such as 1.25. The ratio is operating cash flow divided by total loan payments. A business carrying $96,000 in annual debt service needs $105,600 of operating cash flow to reach 1.10 and $120,000 to reach 1.25.
Is invoice factoring cheaper than a merchant cash advance?
Usually, yes. Factoring sells unpaid invoices at a discount, and the cost depends on how long customers take to pay. A fee of 2.5 percent per 30 days works out to roughly 30 percent annualized, well below the roughly 95 percent effective APR of a 1.35 factor-rate advance repaid over eight months. Factoring fits B2B companies with large, reliable customers on long terms. A bank line of credit is cheaper than both when one is available.
Sources
- *
- Office of the Comptroller of the Currency. "Bank of America: The Humble Beginnings of a Large Bank." OCC History, accessed October 26, 2026. Source for the April 18, 1906 earthquake, the $80,000 in gold and silver coin hidden under crates of oranges, handshake lending from a North Beach wharf, superheated vaults kept shut for weeks, the November 1, 1930 change to Bank of America, its 1949 size (500+ branches, $6 billion, largest bank in the world), Giannini's immigrant and working-class borrowers, and his walking the rows with farmers to sell statewide branch banking. https://occ.treas.gov/about/what-we-do/history/giannini-bank-article-html-version.html
- †
- McKay, Leonard. "The 1906 Earthquake." San Jose Inside, March 27, 2006. Recounts that Giannini stretched a plank across two barrels near the San Francisco waterfront after the quake and lent to borrowers who answered yes to two questions: were they staying, and would they rebuild. https://www.sanjoseinside.com/news/the_1906_earthquake1/
- ‡
- Christian, Ralph J. "National Register of Historic Places Inventory-Nomination Form: Bank of Italy Building." National Park Service, June 1977. Documents the two wagons of money covered with fruit and vegetables and driven to Giannini's San Mateo home, the plank counter on the Washington Street wharf, and the bank reopening within nine days, ahead of other San Francisco banks. https://npgallery.nps.gov/NRHP/GetAsset/NHLS/78000754_text
- §
- Board of Governors of the Federal Reserve System. "FOMC Statement and Decisions Regarding Monetary Policy Implementation." September 16, 2026. The Committee raised the federal funds target range by a quarter point to 3.75 to 4.00 percent on a 12 to 0 vote. https://www.federalreserve.gov/monetarypolicy/files/monetary20260916a1.pdf
- ‖
- U.S. Bancorp. "U.S. Bank Increases Prime Lending Rate to 7.00 Percent." Press release, September 16, 2026. Prime rate raised from 6.75 to 7.00 percent, effective September 17, 2026. https://s203.q4cdn.com/711684571/files/doc_news/U-S--Bank-Increases-Prime-Lending-Rate-to-7-00-Percent-2026.pdf
- ¶
- McCarthy, Charles R. "Client Alert: SBA Issues SOP 50 10 8." Whiteford, Taylor & Preston, May 6, 2025. Effective June 1, 2025: reinstated pre-2021 underwriting, 10 percent equity injection for startups and changes of ownership, full-standby seller notes capped at half the injection, 100 percent citizen or permanent resident ownership, two-year guarantees on rollover equity, no guarantee for investors under 20 percent in full changes of ownership, and CPA statements in place of tax returns in some cases. https://www.whitefordlaw.com/news-events/client-alert-sba-issues-sop-50-10-8-key-changes-impacting-sba-7a-lending
- **
- Coleman Report. "This Just In: SBA Releases SOP 50 10 8.1, Effective October 1, 2026." Coleman Report, August 2026, accessed October 26, 2026. SOP 50 10 8.1 applies to loans numbered on or after October 1, 2026, revises acquisition equity and underwriting standards, allows revolving lines in eligible acquisitions, adds SBA Express flexibility and expands MARC. https://colemanreport.com/this-just-in-sba-releases-sop-50-10-8-1-effective-october-1-2026/
- ††
- Federal Reserve Banks. "2026 Report on Employer Firms." Small Business Credit Survey, March 3, 2026. Source for 6,525 responses, 60 percent applying for financing, 38 percent applying for a loan, line or merchant cash advance, 42/36/22 percent full, partial and no funding, 57 percent full approval at small banks, 60 versus 37 and 32 percent reporting higher-than-expected costs, 56 and 46 percent borrowing reasons, 31 percent with no debt versus 21 percent in 2020, 59 percent personal guarantees, 51 percent business-asset collateral, and reaching customers as the top operational challenge. https://www.fedsmallbusiness.org/reports/survey/2026/2026-report-on-employer-firms
- ‡‡
- National Credit Union Administration. "Quarterly Credit Union Data Summary, 2026 Q2." NCUA, accessed October 26, 2026. Commercial loans of $201.7 billion, up 10.1 percent year over year; total loans up 4.9 percent; 4,214 federally insured credit unions and 146.1 million members. https://ncua.gov/files/publications/analysis/quarterly-data-summary-2026-Q2.pdf
- §§
- U.S. Small Business Administration. "Types of 7(a) Loans." SBA, accessed October 26, 2026. Standard 7(a) up to $5 million with a 75 percent guarantee and 5 to 10 business day SBA turnaround, 7(a) Small up to $350,000 with 2 to 10 business days, SBA Express up to $500,000 with a 50 percent guarantee, and CAPLines maturities up to 10 years. https://www.sba.gov/partners/lenders/7a-loan-program/types-7a-loans
- ‖‖
- U.S. Small Business Administration. "SBA Fuels Main Street Growth with $100 Billion Delivered in FY26." News Release 26-113, November 2, 2026. 56,130 7(a) loans totaling $32.4 billion and 6,075 504 loans totaling $7.1 billion in fiscal 2026, a year in which the 43-day federal shutdown halted 7(a) and 504 lending for part of the year. https://legacy.sba.gov/article/2026/11/02/sba-fuels-main-street-growth-100-billion-delivered-fy26
- ¶¶
- U.S. Small Business Administration. "7(a) Loans." SBA, accessed October 26, 2026. Maximum variable-rate spreads over the base rate of 6.5, 6.0, 4.5 and 3.0 points by loan size tier. https://www.sba.gov/funding-programs/loans/7a-loans
- ***
- U.S. Small Business Administration, Office of Capital Access. "Procedural Notice 5000-876626: Update to SOP 50 10 8, Revised Applicant Ownership Citizenship and Residency Requirements for 7(a) and 504 Loans." SBA, February 11, 2026. Effective March 1, 2026, 100 percent of direct and indirect owners and required guarantors must be U.S. citizens or U.S. nationals, and lawful permanent residents are ineligible. https://www.naggl.org/wp-content/uploads/2026/05/5000-876626.pdf
- †††
- U.S. Small Business Administration. "Procedural Notice 5000-876777: Sunset of SBSS Score for 7(a) Small Loans, Supplemental Guidance." February 20, 2026. SBSS score discontinued March 1, 2026; debt service coverage of at least 1.10 to 1 on a historical or projected basis; scoring models may not rely solely on consumer credit scores. https://www.naggl.org/wp-content/uploads/2026/05/5000-876777.pdf
- ‡‡‡
- National Federation of Independent Business. "NFIB Small Business Economic Trends: September 2026." NFIB Research Center, October 2026, accessed October 26, 2026. Average rate paid on short-term loans of 8.2 percent, up 0.7 points from August, and 22 percent of owners borrowing regularly versus a 34 percent historical average. https://www.nfib.com/wp-content/uploads/2026/10/NFIB-SBET-Report-September-2026.pdf
- §§§
- Equipment Leasing and Finance Association. "New Deal Volumes Headed for Record Year." CapEx Finance Index, September 2026, ELFA news release, October 27, 2026. New business volume up 17.0 percent year to date, credit approval rate up 2.4 points to 77.7 percent (the largest monthly gain since October 2023), and acting president and CEO James Cress on how strong deal volumes have been this year. https://www.elfaonline.org/newsroom/cfi-september-2026
- ‖‖‖
- Internal Revenue Service. "Publication 946 (2025), How to Depreciate Property." IRS, accessed October 26, 2026. 2026 Section 179 limit of $2,560,000 with phaseout above $4,090,000, and 100 percent bonus depreciation reinstated for qualified property acquired after January 19, 2025. https://www.irs.gov/publications/p946
- ¶¶¶
- Callen, Alexander J., and Josh Burlingham. "New York Finalizes Commercial Financing Disclosure Regulations." Goodwin Procter, February 14, 2023. New York's regulations, adopted February 1, 2023, require APR disclosures, including estimates for non-loan products such as sales-based financing, on transactions of $2.5 million or less, and note similar regimes in California, Utah and Virginia. https://www.goodwinlaw.com/en/insights/publications/2023/02/02_14-new-york-finalizes-commercial-financing
- ****
- Cooley, Krista, Francis L. Doorley, Steven M. Kaplan, Eric T. Mitzenmacher, Daniel B. Pearson, and Jeffrey P. Taft. "Connecticut and Florida Join the Fray: Enact Commercial Finance Disclosure Laws." Mayer Brown, July 26, 2023. Florida's law covers commercial financing of $500,000 or less consummated on or after January 1, 2024, requires dollar-cost and term disclosures without a TILA-style rate, and sets fines of $500 per incident capped at $20,000. https://www.mayerbrown.com/en/insights/publications/2023/07/connecticut-and-florida-join-the-fray-enact-commercial-finance-disclosure-laws
- ††††
- Federal Reserve Bank of Cleveland. "Fed Survey: Small Business Optimism Wanes as Performance Metrics Hold Steady." Press release, March 3, 2026. Reports that applications at online lenders rose for the fifth consecutive survey year and are now similar to the rate at small banks, driven by faster decisions and a better chance of funding. https://www.clevelandfed.org/collections/press-releases/2026/pr-20260303-fed-survey-small-business-optimism-wanes-as-performance-metrics-hold-steady
- ‡‡‡‡
- Rapoza Associates for the CDFI Coalition. "General CDFI Fact Sheet." CDFI Coalition, March 2026. 1,383 Treasury-certified CDFIs, more than 109,000 businesses financed by CDFI Fund award recipients in FY 2024, almost $24.5 billion in total loans and investments, and over $8 of private capital per $1 of federal support. https://cdfi.org/wp-content/uploads/2026/03/General-CDFI-Fact-Sheet-March-2026-1.pdf